
Stablecoin Cross-Border Settlement Faces 'Last Mile' Challenges
The U.S. GENIUS Act provides regulatory legitimacy for stablecoins, but ACI Worldwide executive Phil Bruno writes that stablecoins still face 'last mile' challenges in cross-border settlement: local currency conversion relies on domestic banking systems, and there is a lack of interoperability between stablecoins and blockchains, making it difficult to replace existing instant payment networks in the short term.
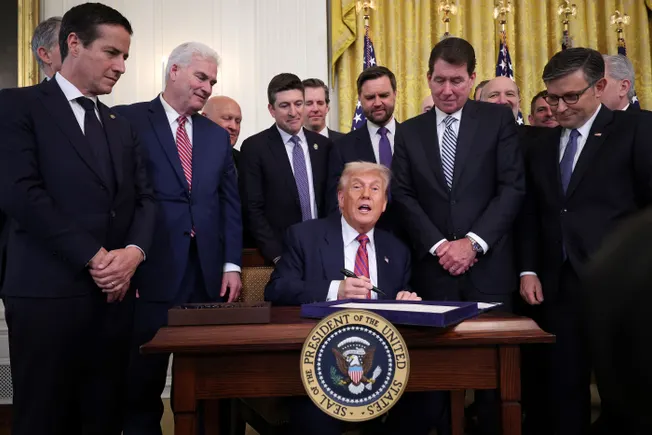
As U.S. President Donald Trump signs the GENIUS Act, the financial services industry is increasingly anticipating stablecoins to transform the global payment landscape. The act aims to establish consumer protections, reserve requirements, and a federal regulatory framework for stablecoin issuers, and more importantly, it adds industry-level credibility and recognition to the potential of stablecoins as reliable payment instruments.
In theory, these digital currencies, pegged to fiat currencies to minimize price volatility, offer an attractive solution to the friction, cost, and delays common in international payments. However, even as the financial services industry embraces innovation, reality often cools enthusiasm—the path to widespread adoption of stablecoins in cross-border settlement is unlikely to be smooth.

Current cross-border payment infrastructure, while significantly improved, still suffers from inconsistencies and high costs. Interbank networks such as correspondent banking and Swift have largely addressed the secure transfer of funds, but countries vary widely in the speed of processing the domestic leg of transactions. Stablecoins promise to solve these issues—for example, by leveraging local real-time or instant payment systems to act as settlement bridges between currency zones, reducing reliance on commercial bank balance sheets and creating faster, more transparent settlement experiences.
In fact,the Bank for International Settlements (BIS)has acknowledged that, with sound governance and regulatory support, stablecoins can facilitate more efficient cross-border fund flows.Project DunbarandProject Helvetiahave both explored multilateral central bank digital currencies and tokenized settlement use cases, hinting at future possibilities.
However, from a practical standpoint, the promise of stablecoins to solve existing problems quickly encounters a series of challenges, the most prominent of which is what we call the 'last mile' problem. Even if stablecoins can act as frictionless intermediaries in parts of the payment journey, local recipients ultimately still need to receive funds in local currency, deposited into local bank accounts or digital wallets. This final conversion step is where existing frictions concentrate—and stablecoins currently do not show a clear advantage here.
The reason is this: local currency conversion still requires integration with domestic banking systems, and many countries already have well-established local clearing and settlement infrastructure. Instant payment schemes, such as FedNow in the U.S., are already operational in over 70 countries, with more following. These systems are designed for speed, resilience, and accessibility. Introducing stablecoins into this mix adds complexity rather than simplification—especially when end users still rely on traditional banking and payment systems for services.
Furthermore, the lack of interoperability among stablecoins and blockchains poses another significant barrier. Cross-border payments involve transferring funds across different jurisdictions, regulatory frameworks, and technical standards. Unless stablecoins can achieve seamless integration with each other and with legacy financial systems, they will struggle to move beyond niche use cases.